

The process of selling a business is the sequence of five stages that takes an owner from the decision to sell to the signing of the sale and purchase agreement (SPA): preparation, documentation, buyer search, negotiation with due diligence, and closing.
Thinking about selling your business? Speak to an M&A adviser and find out what it is worth.
Many owners picture the sale of their company as a dry, technical and almost unmanageable process. It is not: it follows a clear logic in which each stage ends with a specific document or agreement. In ONEtoONE’s experience of mid-market transactions, a complete process usually takes several months and can last up to a year.
What are the stages of selling a business?
Selling a business follows five consecutive stages, and each one prepares the next: if one is done badly, the problem resurfaces later, usually as a cut in the price.
- Preparation and strategy: objectives, a realistic value range and the signing of the sale mandate.
- Sale documentation: blind teaser and information memorandum to present the company to buyers.
- Buyer search: domestic and international mapping, non-disclosure agreements and indicative offers.
- Negotiation and due diligence: letter of intent with exclusivity and a thorough review of the company.
- Closing: binding offer and signing of the sale and purchase agreement (SPA).
Summary table: the 5 stages of selling a business
| Stage | Key document | What to watch |
|---|---|---|
| 1. Preparation and strategy | Sale mandate | Set clear objectives and a realistic value range before talking to buyers |
| 2. Sale documentation | Blind teaser and information memorandum | Present the company transparently, without revealing its identity too early |
| 3. Buyer search | NDA and indicative offers | Open the process to international buyers and create competition |
| 4. Negociation and due giligence | Letter of intent (LOI) and data room | Reach the LOI with the key points agreed and the documentation in order |
| 5. Closing | Binding offer and SPA | Negotiate warranties, price adjustments and deferred payments, not just the price |
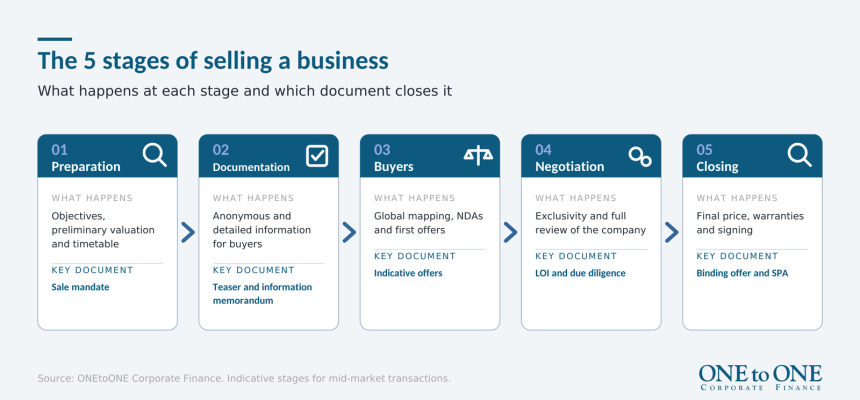
Each stage has a goal, its own participants and a document that closes it. These are the keys to each one.
Cada fase tiene un objetivo, unos protagonistas y un documento que la cierra. Estas son las claves de cada una.
1. Preparation and strategy
Shareholders decide whether to sell 100% or a stake, which type of buyer they prefer and what needs tidying up before going to market. A value range is also estimated with valuation methods such as discounted cash flow or comparable transaction multiples. Remember that shareholders receive the equity value, not the enterprise value. The stage ends with the signing of a sale mandate with the M&A adviser.
2. Sale documentation
The blind teaser presents the sector, size and key figures of the company in one or two pages without revealing its identity. Anyone who shows interest and signs a non-disclosure agreement receives the information memorandum, covering the company’s history, business model, market, team and financial statements. Confidentiality is critical: a leak can unsettle employees, customers and suppliers.
3. Buyer search
The adviser maps trade buyers, private equity funds, family offices and search funds, both domestic and international. The best buyer is not always the closest: it is often an industrial group or an investor from another country for whom the company is a clear strategic fit. Each interested party signs a non-disclosure agreement (NDA) and then submits a non-binding indicative offer with price, payment terms and timetable.
4. Negotiation and due diligence
The seller chooses the buyer with the best fit and signs a letter of intent with exclusivity. The seller’s negotiating power is greater before signing it than after, so it pays to reach it with the key points agreed. The buyer then reviews all the company’s information in a data room:
- Financial: quality of EBITDA, debt and working capital.
- Tax: taxes and contingencies.
- Legal: contracts, litigation and assets.
- Employment: workforce and commitments.
If due diligence uncovers contingencies, the price or the warranties are renegotiated.
5. Closing and sale and purchase agreement
The buyer confirms its binding offer and the parties sign the sale and purchase agreement, which sets out the price and its adjustments, the seller’s representations and warranties, limitations of liability and conditions precedent. Part of the price may be deferred or made conditional on results through an earn-out clause.
Thinking about selling your business?
Speak to an adviser to find out what your company is worth and which buyers could pay the most for it.
Why use an M&A adviser to sell your business?
An M&A adviser brings method, access to buyers and negotiating power, and lets the owner keep running the business while it is being sold.
Most owners sell a company only once in their lives, facing buyers who negotiate acquisitions regularly. Three reasons make the difference:
- Access to buyers: ONEtoONE’s databases cover more than 38,200 buyer groups and 18,200 private equity firms.
- Better price: creating competition between several buyers improves the terms of the offer.
- Confidentiality: the adviser screens candidates before revealing the company’s identity.
Discover our sell-side M&A service and real transactions completed by ONEtoONE.
Conclusion
Selling a business is not a formality but a process of five linked stages. Owners who prepare early, open the sale to buyers around the world and negotiate every clause, not just the price, reach closing on better terms and with fewer surprises.
Frequently asked questions
How long does it take to sell a business?
A complete process usually takes several months and, in ONEtoONE’s experience, can last up to a year.
It depends mainly on preparation, the number of buyers and what comes up in due diligence.
What is a blind teaser?
It is a short document that presents a company for sale without revealing its identity, to gauge buyer interest.
Only those who sign a non-disclosure agreement then receive the information memorandum with the company’s name.
What is the difference between an indicative offer and a binding offer?
An indicative offer is preliminary and non-binding; a binding offer is a firm commitment, usually submitted after due diligence.
The binding offer sets the price and terms that are carried into the sale and purchase agreement (SPA).
What is reviewed in due diligence?
The buyer reviews the company’s financial, tax, legal and employment matters to confirm the information and identify risks.
Organising the documentation before opening the data room reduces surprises and protects the price.
Can you sell a business confidentially?
Yes. The blind teaser, non-disclosure agreements (NDAs) and controlled access to information protect the company’s identity.
The adviser shares sensitive information only with the most serious candidates, in the final stages.
About ONEtoONE Corporate Finance
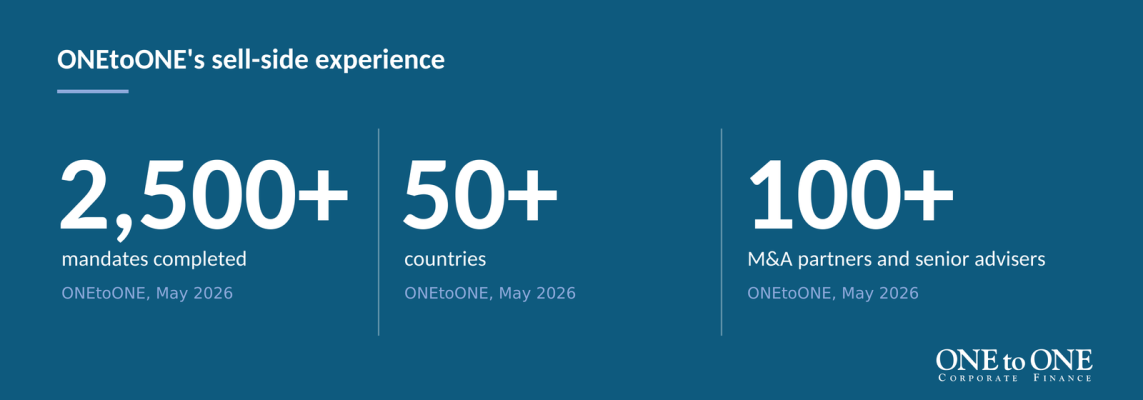
ONEtoONE Corporate Finance is an M&A advisory network specialising in mergers and acquisitions for mid-market companies. With a presence in more than 50 countries, we support business owners and executives in the most important corporate decisions of their careers.